

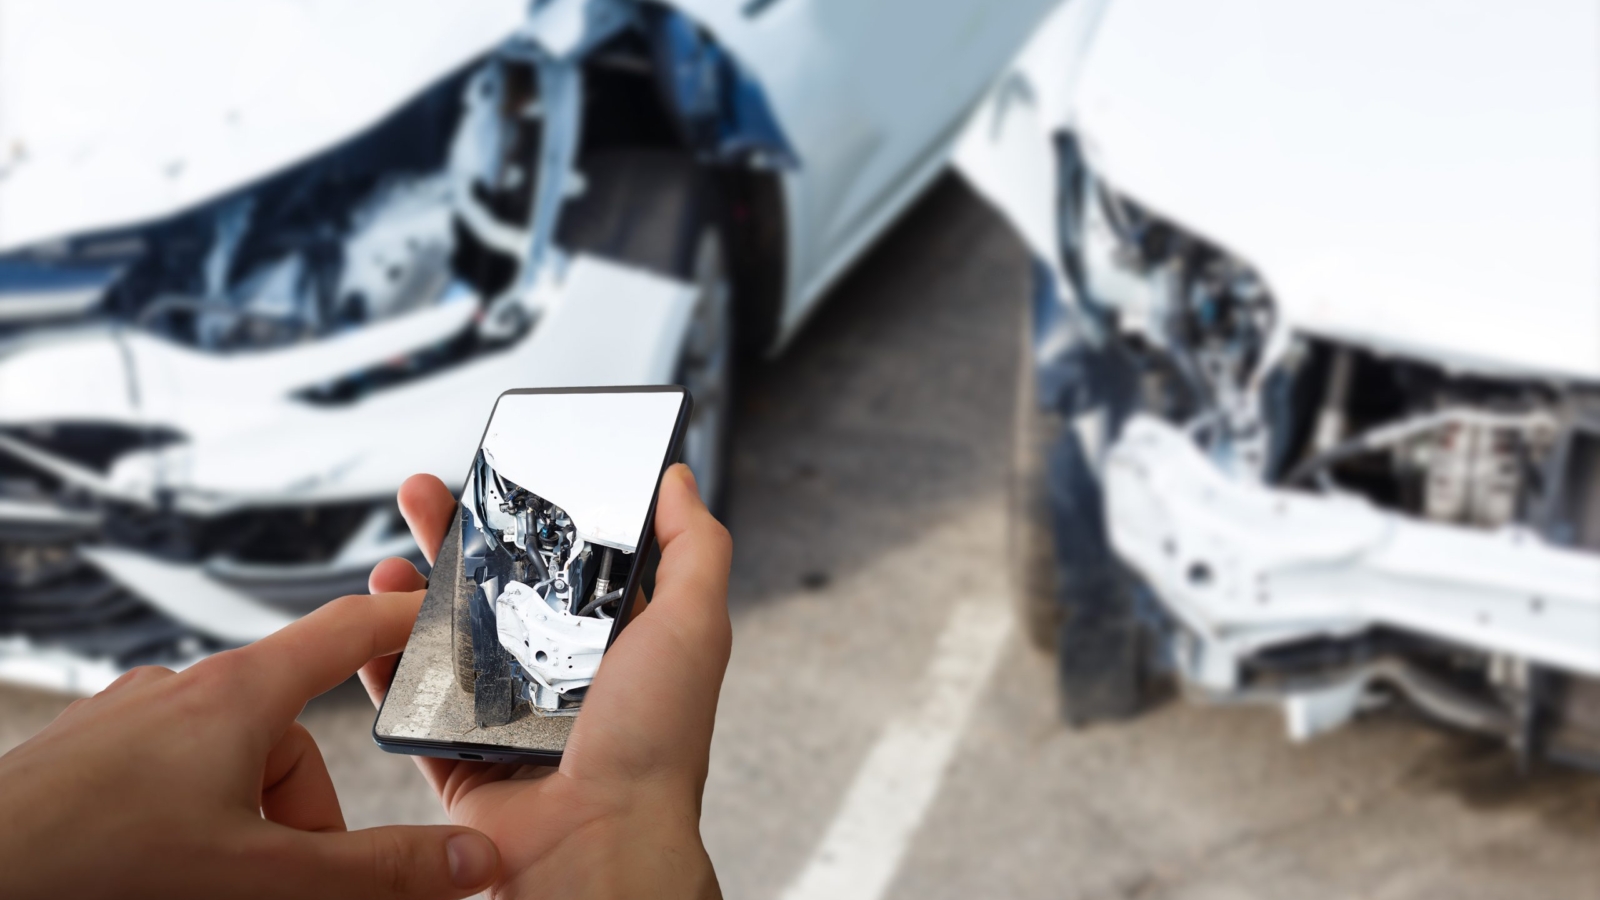
An automobile accident can turn an ordinary day into a sequence of unfamiliar decisions. Drivers may need to address injuries, document damage, exchange information, arrange transportation, and communicate with an insurer while still processing what happened.
Knowing the general structure of a claim can reduce confusion. Although procedures differ by insurer, coverage type, and applicable requirements, most claims follow a recognizable progression from initial reporting to a final determination.
First, Establish Safety
The immediate priority after an accident is the safety of everyone involved. Drivers should check for injuries, contact emergency services when necessary, and follow instructions from appropriate authorities. Vehicles should be moved only when it is safe and lawful to do so.
Once immediate hazards have been addressed, the parties can exchange relevant contact and vehicle information. Photographs of vehicle positions, visible damage, road conditions, and relevant surroundings may help preserve details that could otherwise be forgotten.
Drivers should avoid making assumptions about fault or the final cost of damage at the scene. Early observations are useful, but responsibility and coverage may require additional investigation.
Reporting Creates the Initial Record
A claim usually begins when the insurer is notified of an incident. The report commonly includes the date, time, location, vehicles involved, a description of events, and any known injuries or property damage.
Accurate information matters. Conflicting details, missing documents, or delayed communication can complicate the assessment. Drivers should provide factual descriptions and distinguish what they directly observed from what they believe may have happened.
The insurer may request photographs, a police report where applicable, witness details, repair estimates, or additional documentation. Requirements depend on the circumstances and the policy.
Investigation and Coverage Review
After receiving the report, the insurer reviews the available evidence and determines how the policy may apply. This process can involve examining statements, assessing vehicle damage, reviewing relevant records, and evaluating liability.
Coverage and fault are related but distinct questions. A claim may involve an investigation into responsibility while the insurer separately determines which policy provisions apply to the reported loss.
The presence of an insurance policy does not automatically establish that a particular expense is covered. Exclusions, limits, deductibles, reporting requirements, and other contractual conditions can influence the outcome.
Damage Assessment and Repairs
Vehicle damage may be assessed through photographs, an inspection, a repair facility's estimate, or other approved methods. In some cases, additional damage becomes visible only after repairs begin, requiring a supplemental assessment.
When a vehicle is considered a total loss, the settlement process may differ from an ordinary repair claim. The insurer typically evaluates the vehicle's value under the applicable policy and rules, then accounts for relevant contractual terms and any required adjustments.
Drivers should keep copies of estimates, invoices, receipts, and communications. Organized records make it easier to understand decisions and identify unresolved questions.
Settlement Is Not Always the Final Practical Step
A claim may conclude with payment, an approved repair arrangement, a denial, or another outcome permitted by the policy. Some claims take longer because injuries require ongoing evaluation, liability remains disputed, or additional evidence is needed.
If a decision is unclear, the policyholder can request an explanation of the relevant provisions and the information used to reach the determination. Disagreements may be addressed through the insurer's review process or other procedures available under applicable rules.
A claim is not merely paperwork. It is a structured assessment of an event, the evidence surrounding it, and the financial responsibilities defined by an insurance contract. Preparation, accurate documentation, and clear communication can make that process more manageable.